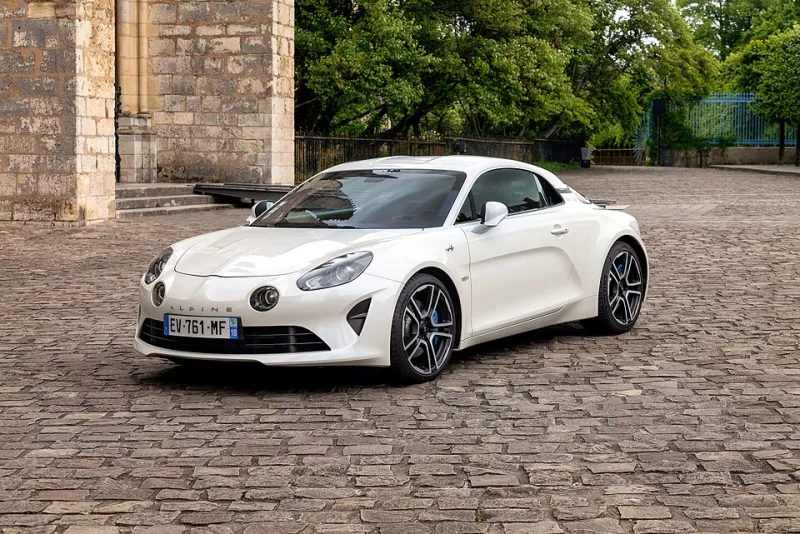
Handing Back the Keys: A Sensible Playbook for Modifying a Leased or PCP Car
Photo: car lease return inspection alloy wheels UK, via ecdn.teacherspayteachers.com
A leased car or a PCP car can feel like yours. You drive it every day, you pay for it every month, and you have opinions about the wheels. But the finance agreement has a long memory. When the keys go back, someone will look at the car with a clipboard and a set of return standards. If you have changed the wheels, tyres or ride height, that is the moment the paperwork starts to matter.
This is not a plea to leave every lease car completely standard. It is a plea to be deliberate. Some changes are easy to reverse and unlikely to cause trouble. Others can follow the car back to the funder and cost you money after you have already said goodbye.
Read the agreement before the shopping basket
Finance contracts vary, but most leased and PCP agreements include conditions about the vehicle's condition, servicing and modifications. The funder owns the car or has a major financial interest in it. They will usually expect it back in a condition that matches their return standards, often based on industry fair-wear-and-tear guidance.
Look for wording about alterations, non-standard parts, bodywork, wheels and tyres. Some agreements are explicit; others rely on general clauses about maintaining the vehicle. If the contract is vague, ask the funder in writing before you buy anything. A quick email that says 'can I fit these wheels and will they need to be removed before return?' is worth more than a forum thread full of guesses.
The low-risk end of the spectrum
Tyre replacement is usually straightforward, provided you stay within the manufacturer's specified size, load rating, speed rating and any specific requirements in the handbook. Replacing worn tyres with quality rubber of the correct specification is maintenance, not modification. Keep the invoices and make sure the sizes match what the car came with.
Floor mats, boot liners and other removable accessories are generally harmless, as long as they do not damage the interior. A set of OEM-spec alloy wheels from the same model range may also be acceptable in some cases, but do not assume. The funder may still treat non-original wheels as a modification, even if they look factory-fit.
Where the trouble starts
Aftermarket alloys are the classic grey area. They can change the car's appearance, insurance profile and return condition. If they are a different size, offset or style from standard, expect questions. If they are cheap replicas with dubious load ratings, expect more than questions. The same applies to spacers, lowering springs, coilovers and anything that alters the ride height or suspension geometry.
Tyres can be a problem too if you go off-spec. Fitting wider tyres, a different profile or a lower speed rating may look harmless but can breach the finance terms and your insurance policy. Insurance notification is not optional. Most UK insurers require you to declare modifications, including cosmetic ones in some cases. An undeclared set of alloys can complicate a claim, even if the wheels had nothing to do with the incident.
Insurance is part of the modification decision
Before you fit anything, ring your insurer or check the policy documents. Ask whether the change is acceptable, whether it affects the premium and whether it needs to be listed. Some insurers are relaxed about factory-option wheels and correct-spec tyres; others are not. If you are on a lease or PCP, you may also need to tell the funder, not just the insurer.
The practical rule is simple: if you would not be comfortable explaining the change to both the insurer and the finance company in writing, do not fit it.
Keep the original parts and document everything
The safest modifications are the reversible ones. If you fit aftermarket alloys, keep the original wheels and tyres. Store them properly, label them and photograph them before they go into the garage. If you change suspension, keep the standard parts. If you fit anything electrical or cosmetic, keep the receipts and take before-and-after photos.
Documentation matters at return time. A folder with the finance agreement, insurer notification, wheel and tyre specifications, alignment printouts and photos of the standard parts can save an argument. It also helps if you sell the car privately at the end of a PCP agreement, because a buyer will want to know what has been changed and why.
Return day is not the time to improvise
Return-condition charges often relate to excess wear, damage or missing standard equipment. Non-standard wheels may be treated as missing original equipment if you do not put the standard set back on. Scuffed aftermarket alloys may be judged against the return standard even if you plan to remove them. If you have lowered the car, the funder may require it to be returned to standard height before inspection.
Plan the reversal before you need it. Book a garage, keep the original parts accessible and allow time to swap everything back. Do not leave it until the morning of collection.
The sensible bottom line
A leased or PCP car is not a blank canvas. It is a long-term rental with a contract attached. Correct-spec tyres and removable accessories are usually low-risk. Aftermarket wheels, suspension changes and off-spec tyre sizes need written approval, insurer notification and a clear reversal plan.
If you want to modify a car without those constraints, buy one outright. If you are keeping the finance car, modify with one eye on the return envelope. The best modifications are the ones you can undo without leaving a trace, a charge or an awkward conversation.